The breakdown of a long-term relationship is one of life's most difficult transitions.
Beyond the emotional impact, it can affect our sense of stability, our routines, and our overall well-being. It's a period of major change. It often requires us to adjust to a new reality while making decisions about the future.
From resetting your monthly budget, dividing assets, and planning for the long-term, what you decide now can shape your finances for years to come.
Knowing how your pension may be affected by a relationship breakdown is key to your financial future. You’ll want to make sound decisions with your finances. To help, we’ll discuss:
- Why pensions are part of the conversation.
- How a relationship breakdown may affect your pension benefits.
- What role CSS plays in the process.
- What steps to take if you’re going through a relationship breakdown.
Let’s look at how your pension benefits may be affected as you go through a separation or divorce.
Why pensions come up
We often think of a pension as future income. But when a relationship ends, your pension benefits may also be treated as property.
Like a home, savings, or investments, pension benefits gained over the course of your marriage may be considered family property.
And depending on your age, this could include your current CSS account or your CSS retirement income.
For many of us, our retirement savings may be one of our largest assets. As a result, pension benefits often become part of the discussion around family property and financial settlements.
However, this does not necessarily mean your entire pension will be divided.
Often, the focus is on the part of your pension earned during the course of your marriage or common-law relationship.
Jurisdiction matters
Pension division can be complicated because more than one set of rules may apply.
Family property laws help decide how assets are divided, while pension laws guide how CSS can value and administer pension benefits.
Sometimes, those rules may come from different provinces or jurisdictions.
For example, a member may live in one province, earned pension benefits in another, and rely on family property laws from a third. This means the pension legislation can vary depending on your situation.
Jurisdictions may have different rules on:
- Who qualifies as a spouse or common-law spouse.
- Whether pension division is needed or optional.
- How pension benefits are valued.
- What wording is needed in court orders or agreements.
- How benefits can be divided.
- Any time limits or administrative requirements.
This is why two similar situations often have quite different outcomes.
CSS offers jurisdiction-specific resources to help you with your situation.
How CSS becomes aware of a relationship breakdown
If you’re separated, it’s important to let us know. You can contact us by phone, email, or by updating your marital status by completing the Member Information Change form.
Keep in mind that whenever we use the term ‘spouse,’ it also refers to a common-law partner.
Once CSS becomes aware of a change in your marital status, we may flag your file while the matter is reviewed. This helps ensure your pension benefits are managed correctly. Plus, we can’t do anything until the legal requirements have been met.
Requesting a valuation
If you find yourself separated from your spouse, you may be asked to get a pension valuation from CSS.
A valuation provides information about the dollar value of your pension benefit. As a financial asset, the valuation of your pension benefit may be used in the division of assets considered family property.
A valuation is a key step. Yet, it’s important to understand what a valuation does – and does not do.
A valuation does not divide a pension.
It is simply information used during the legal process to decide a financial settlement. CSS can’t do anything with your pension until we receive and review the required legal documentation.
How the process typically works
Most relationship breakdowns often follow the path shown below.
Step 1 – The relationship ends. The parties begin addressing legal, financial, and family matters.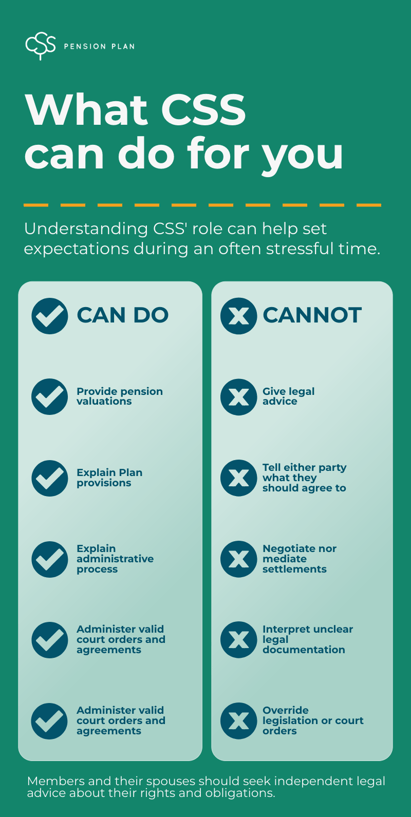
Step 2 – Information is gathered by both parties. A pension valuation may be requested as part of the process to collect financial information from you and your spouse.
Step 3 – Legal advice is obtained. The parties work through the legal process to decide how their family property will be addressed.
Step 4 – An agreement or court order is completed. The legal document shows how assets, including pension benefits, will be treated.
Step 5 – Documentation is provided to CSS. We review the legal document to ensure it satisfies legislative and administrative requirements.
Step 6 – CSS administers the outcome. Whether your pension benefits are to be divided or not, we will conduct the division based on the legislation, Plan provisions, and legal documentation.
Not every relationship breakdown results in a pension division
A common myth is that every pension must be divided whenever a relationship ends.
This is not always the case.
In some cases, both parties may agree to have the Plan member keep their entire pension benefit. The member's spouse may choose to waive their entitlement. The options will depend on the pension legislation applicable to the couple's jurisidiction. In other situations, a court order, legislation, or an agreement may require the pension benefits to be divided.
Both outcomes are possible.
CSS does not decide what happens to your pension benefits. Rather, we carry out the formal agreement as noted above.
A relationship breakdown can happen at any life stage
Like most members, you may believe pension division affects only active employees. In reality, relationship breakdowns happen to couples at every age and stage of life.
Active members: They’re currently working and contributing to the CSS account. Their pension funds may be subject to review as part of the process.
Deferred members: They have left their CSS-participating employer and haven’t started to withdraw funds from their CSS account.
Retired members: They are receiving either a Variable Benefit payment or a Monthly Pension. Like the member groups above, the retiree’s pension benefit may be subject to review. Retirement scenarios are more complex as we discuss below.
What happens if you’re already receiving a pension payment from CSS?
When we do workshops, members often ask what happens to a retired member’s pension benefit if they become separated or divorced.
This is a common question because retirees are receiving a retirement income from either a Variable Benefit payment or Monthly Pension.
The solution is not as simple as you may think.
Many retirees believe they can simply remove their former spouse from their pension arrangement. However, this is not the case.
When a member retires, they select a form of pension. Depending on their option, the contract outlines CSS’ contractual rights and obligations to the retired member. Their contract may be for their lifetime, and after their death, if applicable.
Once a pension payment starts, the contract cannot be changed by simply asking us to remove a former spouse from their pension contract.
Retired members must go through the same legal process to settle their family property.
Why transactions may pause
You may be surprised when a transfer, withdrawal, retirement election, or beneficiary update does not go ahead.
When CSS becomes aware of a relationship breakdown, your file may be reviewed before processing certain transactions. This helps ensure your pension benefits are administered correctly, and the rights of all parties are protected.
While delays can be frustrating, these reviews help prevent errors that could create problems later for you, the member, your former spouse, or beneficiaries.
What happens to your designated beneficiaries?
You may believe that your former spouse is automatically removed as the primary beneficiary on your pension benefits. They are not.
Beneficiary designations, survivor rights, and pension division rights are separate concepts. Each may be overseen differently due to legislation and legal documentation.
We can’t emphasize this enough: Always review your beneficiary designations following a major life event.
You may also want to seek legal advice around beneficiaries – depending on your personal situation.
Final takeaway
A relationship breakdown is a difficult process. However, knowing how your pension benefits fit into the bigger picture can help reduce uncertainty during this challenging time.
The process takes time. Be kind to yourself and take it step by step.
The most important things to remember are:
- Pension benefits may be subject to division following a relationship breakdown.
- More than one set of laws may apply.
- A valuation does not divide a pension.
- Not every relationship breakdown results in a pension division.
- CSS requires legal documentation before we can divide pension benefits.
- CSS administers pension benefits by applicable legislation, Plan provisions, and valid legal documents.
If you have questions about how a relationship breakdown may affect your CSS Pension Plan benefits, contact us. We're here to explain the process, answer your questions, and help you understand what may be needed.
Disclaimer: This article is provided for informational purposes only and does not constitute legal advice. For advice regarding your specific situation, please consult a qualified legal professional.