We've all been in this situation before. We chat with co-workers and friends about a topic and walk away believing the information we've received was accurate.
This happens a lot when talking about the ins and outs of a pension plan. Many of us, who have worked in the pension industry for years, have seen many members mislead or misinformed by their co-workers or friends.
Today, we’re going to talk about the five most common myths about the CSS Pension Plan.
To ensure we have our facts right, we’ve turned to the experts – our CSS Retirement and Pension Advisors! The CSS Advisory Team is here to ensure you’re getting the most accurate information about your Plan.
MYTH 1: I’ve heard I must take an annuity (Monthly Pension) if I decide to stay with CSS after I retire.
FACT: CSS offers you two different income options: a Monthly Pension or a Variable Benefit (VB) payment (depending on your jurisdiction*). Each option has its benefits.
These retirement income options are intended to give you flexibility so you can choose the option best suited to your situation and retirement goals. Whatever you do – don’t choose an option because your wife’s brother took the so-and-so option when he retired.
“Most members know they’re entitled to a retirement income from CSS. However, many wrongly assume they have no option but to take an annuity,” says Rhonda Rodh, CSS Retirement and Pension Advisor.
A Monthly Pension provides you with a fixed monthly payment for life. Depending on your marital status, you can choose between a Single Life Pension and the Joint and Last Survivor Pension. Plus, you have an option to add a guarantee period.
If you have a spouse, a key benefit of the Monthly Pension option is knowing that if you predecease your spouse, they are entitled to a survivor pension for life.
Variable Benefit (VB) payments are different than the Monthly Pension option. VB payments are periodic withdrawals (either monthly or annually) from your CSS account. Your payments can be changed over time – giving you a lot of flexibility in retirement. However, the downside is that you are not guaranteed income for life.
On the upside, the VB payment option allows you to stay invested in the Plan’s investment funds – offering you further growth potential while you’re retired.
VB payments are similar to a Life Income Fund (LIF) or Prescribed Registered Retirement Income Fund (pRRIF) offered by your credit union or bank.
You’re also free to set up retirement income payments outside of CSS with your financial institution when you retire – the choice is yours.
**VB payments are available in the following jurisdictions only: AB, BC, MB, NS, ON, SK and Federal.
Visit our Retirement income options page for more details about your CSS options.
MYTH 2: A couple of co-workers told me I cannot leave my CSS pension funds to my spouse and/or survivors.
FACT: This is a common misconception. Your survivor benefits will vary depending on the CSS retirement income option you choose at retirement.
"No matter which option you choose, you have the flexibility to ensure your beneficiary designation fits your personal situation," says Michael McGuffin, CSS Retirement and Pension Consultant. "And you can always discuss your options with our CSS Advisory Team."
If you have a spouse (married or common-law) and you pass away before you retire, your spouse has first claim to your pension funds – even if you chose someone else as your beneficiary (e.g., your children).
Your spouse can waive their entitlement by signing a spousal waiver form. If your spouse signs the waiver (or if your spouse dies before you), any named beneficiaries will then receive your CSS pension benefit.
If you die after you retire, your survivor benefits will depend on which CSS retirement option you chose.
Here’s a brief overview of what happens under each retirement option.
Scenario 1: If you chose the Monthly Pension and you predecease your spouse:
- If you have a spouse, we will assume you opted for the Joint and Last Survivor Pension. Therefore, upon your death, your spouse will receive a monthly survivor pension payment for the rest of their life.
- If you also chose a guarantee period and died within that period, your spouse would receive the full pension payment until the end of the guaranteed period. After that, your spouse would then receive a monthly survivor pension payment for the rest of their life.
Scenario 2: If you chose the VB payment option and you predecease your spouse:
- Your surviving spouse is automatically entitled to all the funds left in your VB account, if any, when you die.
- CSS will contact your spouse with a few options. They can continue to receive the VB payment, convert it to a Monthly Pension, or transfer the balance out of the CSS Pension Plan.
- If you don’t have a spouse (or your spouse waived their entitlement), any balance left in your VB account is paid as a taxable lump sum to your beneficiary or estate.
Are your survivor benefits up to date? We recommend you review the beneficiary section on your statement each year and update, if required.
Visit our Arranging survivor benefits page today to learn more about this topic.
Myth 3: It’s not easy to manage my investments. I wish CSS would offer retirement planning services.
FACT: You may be surprised to learn we’ve been offering retirement planning services at CSS since 2014!
Our CSS Advisory Team is here to help you every step of the way. They’re here to answer any questions you may have about your pension plan or retirement options. They also lead our workshops and webinars.
“I didn’t realize CSS had advisors making calls to members before I joined the team,” says Shontelle Flaman, who joined CSS as a Retirement and Pension Advisor in 2022.
And the best part – our Advisors are Certified Financial Planner® professionals who don’t receive commissions. Our Advisors are here to ensure you know how your Plan works and understand your options no matter where you are in your journey to retirement.
We encourage you to contact CSS and connect with our Advisory Team today. They’re here to answer any pension or retirement-related questions. You can email them a question or arrange a meeting by phone, virtually, or in person – whichever works best for you.
Myth 4: I heard I can’t change my CSS investments to suit my level risk tolerance.
FACT: First, not all CSS members are the same. This is why you have the option to set an investment mix that’s right for you – rather than following the same path as your co-workers.
We offer four investment funds – the Balanced Fund, Equity Fund, Bond Fund and Money Market Fund.
You have the option to invest in any or all of the four investment funds. You can move as much or as little of your pension funds at any time. This includes inactive members too.
“Often, new members don’t pay much attention to their pension account early on,” says Jessica Kreutzer, CSS Retirement and Pension Advisor. “Years go by before realizing they could’ve created a customized portfolio more aligned to reaching their financial goals."
Thinking of reallocating your CSS investment funds? Before making any changes, we highly suggest you complete our online Risk tolerance estimator. Or contact one of our Retirement and Pension Advisors for guidance.
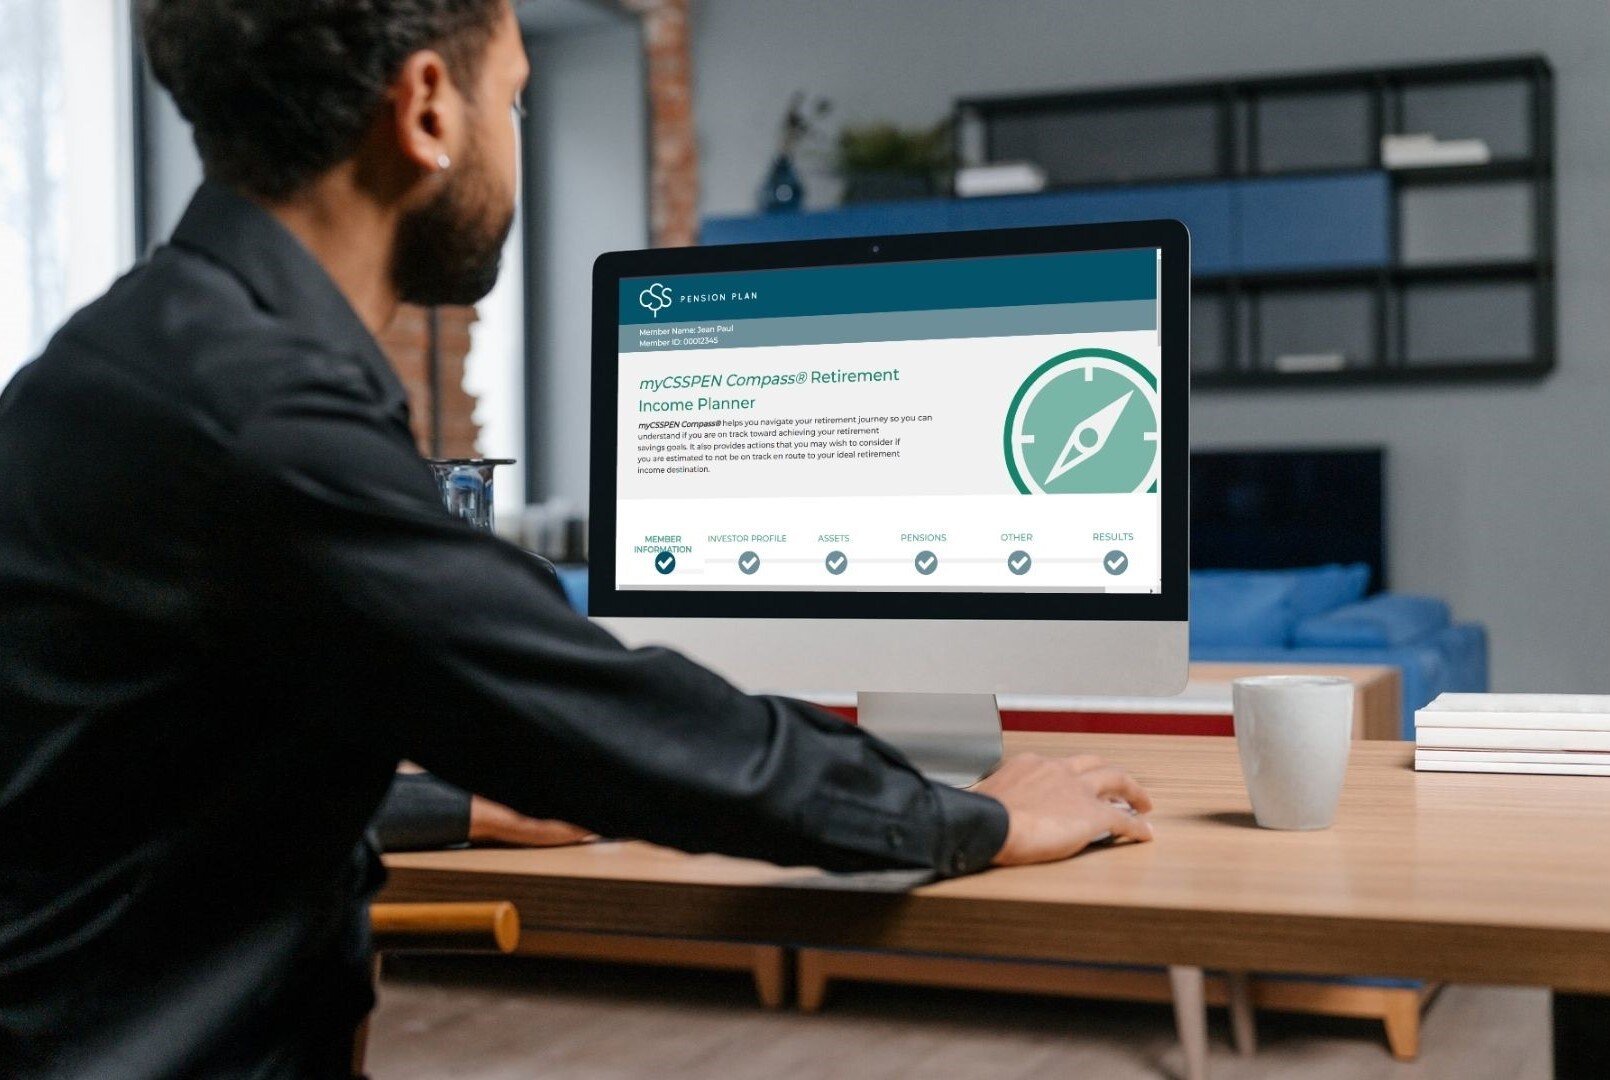
Still want to make a change? Complete the online Investment instructions form (available in myCSSPEN) anytime you want to re-allocate your funds.
Myth 5: Why do I have to retire based on the retirement date shown on my pension statement?
FACT: As a CSS member, you can choose to retire at age 50, 60 or 71 – or somewhere in between. It’s up to you!
Here’s why you may think otherwise. On the first page of your annual CSS pension statement, it shows a normal retirement date and an early retirement date. You might assume you have to retire according to these dates, but that’s not the case.
At CSS, the normal retirement age is 60.
You may qualify for early retirement when you reach age 50 or earlier. To do so, your age plus years of continuous service with one or more participating CSS employers must equal a factor of 75.
If you decide to work past age 60, you and your employer will continue contributing to the Plan until your employment terminates or until November 30 of the year you turn age 71 – whichever comes first.
If you’re a few years from your target retirement date, start putting a retirement plan together. We suggest you visit the Retiring page on our website and review our Ready to Retire booklet, which gives you a detailed overview on the retirement process.
Final takeaway
Co-workers and friends have good intentions when sharing pension information. However, their pension plan may not be the same as yours. Even if you’re in the same plan, most of us have different financial goals and situations to consider. The best thing you can do is connect with your Plan. Visit the CSS website as a starting point! If you’re still unsure, contact us by phone, email or visit us in person. We’re here to help on your journey to retirement.